A fire or flood doesn’t just damage a structure. It scrambles the sequence of decisions a homeowner normally makes over years into a matter of weeks, often while insurers, adjusters, contractors, and sometimes a mortgage servicer are all asking for something different at once. That collision of urgency and complexity is what makes reconstruction feel unmanageable. The fix isn’t optimism. It’s structure: a written scope, verified permits, a milestone-based contract, and a formal closeout, in that order. Homeowners who insist on paperwork at each stage move through recovery with dramatically less friction than those relying on a contractor’s verbal promises.
Why Rebuilding Feels Overwhelming, and How a Step-by-Step Process Fixes That
Rebuilding after major damage feels chaotic because multiple parties (insurer, lender, contractor, code official) each control a piece of the timeline, and none of them is responsible for the whole picture. Breaking the process into a documented sequence, with each stage verified before the next begins, gives homeowners a single reference point and reduces the chance of disputes over money or scope.
Every one of the disputes that drag rebuilds into months of delay traces back to something that was agreed to verbally instead of in writing: a scope that was never itemized, a permit nobody confirmed, a payment released before work was inspected. None of these failures require bad faith on anyone’s part. They happen because rebuilding compresses a normally slow process into a stressful sprint, and paperwork is the first thing people skip when they’re exhausted. Treating the rebuild as a sequence of gated steps, where you don’t move to step four until step three is documented, removes most of the guesswork that causes those disputes in the first place.
Step 1: Make the Property Safe and Document Everything First
Before any reconstruction planning begins, a damaged property needs a safety and habitability assessment, followed by full documentation of the damage (photos, moisture readings, structural notes) before cleanup or repairs start. This record becomes the foundation for insurance claims, contractor scopes, and any code-upgrade discussions later in the process.
The first question after fire, flood, or storm damage isn’t “who do I hire to rebuild?” It’s “is it safe to go back inside?” Standing water, compromised framing, exposed wiring, and airborne contaminants like mold or asbestos fibers can make a structure unsafe long before it looks unsafe. This is also the moment when documentation matters most, because insurers and future contractors will both ask for evidence of the damage’s original condition, not its condition after weeks of secondary deterioration. Photograph everything before touching anything you’re not sure about, and keep a written log of dates, observations, and who was on-site.
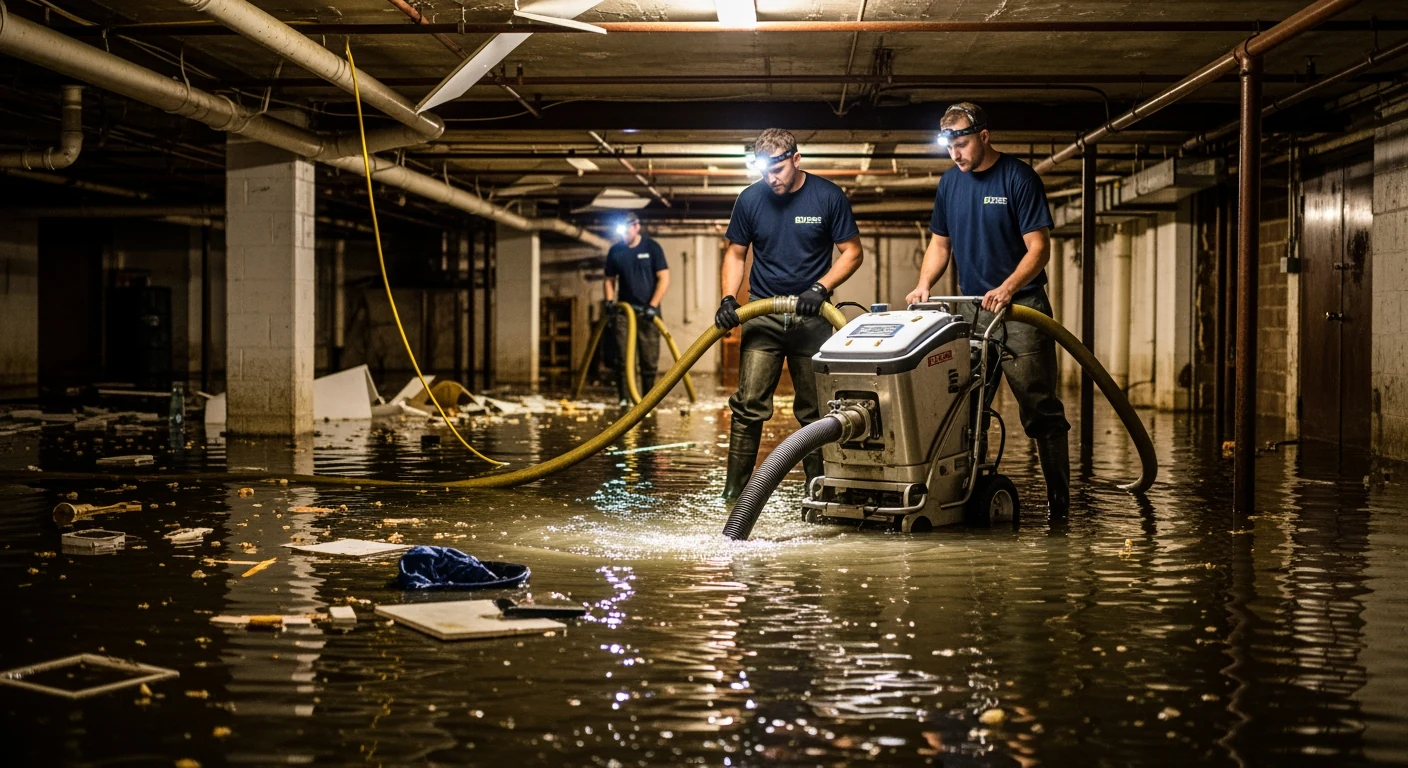
This is precisely the stage where a licensed restoration team, not a general contractor, should be the first call. Stabilization work such as water extraction, structural drying, mold and asbestos assessment, and securing the building envelope has to happen before a reconstruction scope can even be written accurately. Skipping this step, or letting a contractor eyeball it instead of testing it, is how homeowners end up rebuilding over problems that were never actually resolved.
If your property has active water, fire, mold, or structural damage, stabilization and documentation need to happen before any rebuild scope is written. Upper Restoration is available 24/7 across the tri-state area with EPA, IICRC, and NYS-licensed teams.
Step 2: Coordinate Insurance, Mortgage, and Funding Before Signing Anything
Homeowners should confirm with both their insurance company and mortgage servicer how and when funds will be released before committing to a contractor, since claim payouts are often disbursed in stages tied to inspections. The Consumer Financial Protection Bureau recommends requesting a mechanic’s lien waiver from contractors at the start of the project and at each subsequent phase.
Insurance and mortgage timelines rarely match a contractor’s proposed schedule, and that mismatch is where a lot of rebuilds stall. If your loan is escrowed, your servicer likely releases funds only after specific inspection milestones, which means a contractor asking for a large deposit before that first inspection is asking you to front money the loan hasn’t released yet. Get the release schedule from your servicer in writing before you negotiate payment terms with anyone.
Questions to ask your insurer before signing a contractor agreement: Does my policy cover the full scope, or only partial repairs? Am I being paid on a replacement-cost or actual-cash-value basis, and does that change once work is complete? Does my policy include code-upgrade coverage if the rebuild must meet current standards? What documentation does the insurer require before releasing each payment installment? Will payments be issued as joint checks with my mortgage servicer?
Step 3: Confirm Permits, Codes, and Whether Your Rebuild Must Meet a Higher Standard
Permits are frequently required even for components that seem routine, including roofs, siding, plumbing, HVAC systems, septic systems, and demolition itself, and homeowners should contact local building officials directly to confirm what applies to their property. FEMA also advises that construction should not begin until required local permits, including floodplain-management approvals where relevant, have been obtained.
Substantial damage can trigger a legal obligation to rebuild to current code, not the code your home was originally built under. This applies most often to flood-prone properties, where local floodplain-management rules may require elevation or other upgrades once damage crosses a defined threshold. Confirming this before you finalize a scope of work matters, because it can change both the project cost allocation and whether code-upgrade coverage under your policy applies. FEMA’s contractor checklist specifically lists confirming permit responsibility, and ensuring the general contractor consults the local code official, as items homeowners should verify before work starts. FEMA has also stated plainly that it does not endorse or authorize specific contractors, which makes any contractor claim of “FEMA-approved” status a clear signal to look elsewhere.
Regional permit notes. NYC: the Department of Buildings distinguishes between New Building applications and Alteration Type 1, 2, and 3 filings, and a rebuild may require plan approval plus a new or amended Certificate of Occupancy or Letter of Completion. Long Island: permitting is typically handled at the town or village level, so requirements vary by municipality. New Jersey and Pennsylvania: permit rules are set municipally, so confirm directly with your local building department rather than assuming statewide uniformity. Connecticut: the Department of Consumer Protection is explicit that the homeowner remains ultimately responsible for confirming a permit is in place, even if a contractor agreed to file for it.
Step 4: Build a Written Scope of Work and Choose a Qualified Contractor
A written scope of work should separate repairs that restore the property to its pre-loss condition from any improvements the homeowner is choosing to add, since insurers only fund the former and mixing the two creates disputes over what’s covered. The CFPB recommends asking prospective contractors whether they carry general-liability insurance and workers’ compensation coverage, and clarifying up front who is responsible for pulling permits.
Vetting a contractor for a disaster rebuild is different from vetting one for a kitchen remodel, mostly because the financial stakes and timeline pressure are both higher. Verify licensing and insurance directly with the issuing state or local authority rather than taking a certificate at face value, and ask for references from projects of comparable scope completed in the last year. FEMA’s rebuilding guidance also recommends confirming that a contractor is local, since familiarity with your specific jurisdiction’s permitting and floodplain rules matters more here than it would on an ordinary renovation.
| Category | Repair-to-Pre-Loss Condition | Owner-Selected Improvements |
|---|---|---|
| Funding source | Typically covered by insurance claim proceeds | Paid out-of-pocket by homeowner, unless a code-upgrade endorsement applies |
| Scope documentation | Tied directly to pre-loss photos, measurements, and specifications | Listed separately as owner add-ons or upgrades |
| Change order impact | Rarely triggers a change order unless conditions differ from estimate | Frequently the source of change orders and cost disputes |
| Insurer negotiation | Straightforward once damage is documented | Insurer generally uninvolved; homeowner negotiates directly with contractor |
Red flags in a contractor. Demands for a large upfront payment before any inspection has occurred. Refusal to put the scope of work in writing. Discouraging you from pulling permits, or suggesting the work is “too minor” to require one. Any claim of “FEMA-authorized” or “FEMA-approved” status, since FEMA does not endorse specific contractors.
Step 5: Lock In a Milestone-Based Contract and Realistic Schedule
A milestone-based contract ties each payment to a specific, inspected stage of completion rather than to a calendar date, which protects homeowners from paying ahead of finished work. Realistic schedules should also account for permit review time, inspection scheduling, and material lead times, all of which are common causes of rebuild delays that have nothing to do with the contractor’s crew speed.
A schedule that looks tight on paper often falls apart at the permit office, not the job site. Municipal review times vary widely, and inspections have to be scheduled and passed before the next phase of work can legally proceed. Build buffer time into your expectations around framing inspections, rough electrical and plumbing inspections, and final sign-off, rather than assuming the contractor’s proposed end date already accounts for those delays.
Step 6: Track Inspections, Communicate Weekly, and Manage Change Orders
Every inspection result and every change to the original scope should be documented in writing and dated, since verbal change orders are the single most common source of billing disputes on rebuild projects. A short weekly check-in with the contractor, even a five-minute call, keeps small scope questions from becoming large disputes later.
Change orders aren’t inherently a problem. Hidden damage discovered mid-project is normal, especially after fire or water intrusion, and legitimate scope changes will happen. What causes disputes is a change that was agreed to verbally and never priced or signed before the work was done. Require a written, signed change order for anything outside the original scope, with the added cost and schedule impact spelled out, before that work proceeds.
Step 7: Close Out the Project the Right Way
Closeout means confirming final inspections have passed, obtaining any required Certificate of Occupancy or Letter of Completion, collecting final lien waivers from the contractor and subcontractors, and reconciling the last payment against the completed scope. Skipping this step leaves homeowners exposed to liens or unresolved code issues discovered after they’ve already released final payment.
The final lien waiver matters as much as the first one. The CFPB recommends collecting a mechanic’s lien waiver at project start and at each subsequent phase, precisely because a subcontractor who wasn’t paid by the general contractor can, in many states, place a lien against your property even after you’ve paid in full. Don’t release the final payment until you have that waiver, the final inspection sign-off, and a completed punch list in hand.
When to Call a Professional Restoration Team First
Before any reconstruction scope is written, a licensed restoration company should assess and stabilize the property, handling water extraction, structural drying, and mold or asbestos testing so that the rebuild is planned around verified conditions rather than assumptions. This step protects both the accuracy of the insurance claim and the safety of everyone entering the property.
Upper Restoration works this stage specifically: emergency stabilization, environmental testing, and documentation that a contractor can later build a clean scope around, not full reconstruction itself. Getting that sequence right, restoration first, documentation second, contractor and rebuild third, is the single biggest factor in whether a rebuild finishes on a reasonable timeline or drags on for a year over disputes that could have been avoided.
Frequently Asked Questions
Is it safe to go back into my home after major fire or flood damage?
Not always. Standing water, compromised structural elements, exposed electrical systems, and airborne contaminants like mold or asbestos fibers can make a property unsafe even when visible damage looks minor. A licensed restoration or inspection professional should assess the property before extended re-entry, particularly after flooding or structural fire damage.
Do I need a permit for repairs that seem minor, like replacing siding or a roof section?
Often, yes. FEMA notes that permits may be required for components that seem routine, including roofs, siding, plumbing, HVAC, and septic systems, as well as for demolition. Requirements vary by municipality, so homeowners should contact their local building department directly before starting any repair work.
Does major damage mean I have to rebuild to a higher code standard than before?
It can. Substantial damage, particularly in flood-prone areas, may trigger local floodplain-management requirements to rebuild to current code rather than the original standard. Homeowners should confirm this with local building and floodplain officials before finalizing a scope of work, since it affects both cost allocation and potential insurance coverage.
Who is responsible for pulling permits, me or my contractor?
This varies by state and municipality, and homeowners should confirm it explicitly rather than assume. Connecticut’s Department of Consumer Protection, for example, states that the homeowner remains ultimately responsible for confirming a permit is in place, even if the contractor agreed to file for it.
What is a mechanic’s lien waiver and why does it matter?
A mechanic’s lien waiver is a document from a contractor or subcontractor confirming they’ve been paid for completed work and waiving their right to place a lien against the property for that amount. The CFPB recommends collecting one at the start of a project and at each subsequent phase, including at final payment.
How long does a full reconstruction typically take?
Timelines vary widely depending on the extent of damage, permit review times, inspection scheduling, and material availability. Rather than relying on a fixed estimate, homeowners should build buffer time into their expectations around permitting and inspection stages, which are common sources of delay unrelated to actual construction speed.
Should I call a restoration company or a general contractor first after major damage?
A licensed restoration and remediation team should typically be the first call. Stabilization tasks like water extraction, structural drying, and mold or asbestos testing need to happen before an accurate reconstruction scope can be written, and delaying this step can worsen damage or create unsafe conditions.
Sources
- FEMA, “Contact Local Officials Before Rebuilding” (2024)
- FEMA / National Flood Insurance Program, “Rebuilding Safer & Stronger After a Flood” (2022)
- FEMA, “Checklist to Ask Your General Contractor”
- Consumer Financial Protection Bureau, “How Can I Find and Work With Contractors to Rebuild After a Disaster” (2024)
- Consumer Financial Protection Bureau, “Start Recovering and Rebuilding Your Financial Life” (2025)
- New York City Department of Buildings, “Acquire Permits”
- Connecticut Department of Consumer Protection, “Building Permits”
- FEMA, “Building Codes Toolkit”
This content is for general informational purposes only and is not legal, medical, or insurance advice. Remediation scope, timelines, and costs vary by site conditions. Contact Upper Restoration for a professional assessment. Licensing and certifications apply per jurisdiction.